Fixed Income in Focus:
The fixed-income market traded with a broadly bearish bias during the week, shortened by Thursday’s Independence Day holiday. Profit-taking dominated FGN bonds across the 2031s–2038s, pushing average mid-yields higher by c.38bps from Monday’s opening to Friday’s close. Selective demand for the 2032s and 2033s midweek offered some respite, but renewed selling on Friday reinforced the bearish tone. Treasury bills remained relatively muted, with modest yield increases in September maturities, while the June benchmark closed unchanged.
Demand was firmer in the OMO segment, where Tuesday’s auction attracted c.₦6.40tn in subscriptions against c.₦4.69tn allotted. The 266-day bill led demand at 1.51x subscription-to-allotment cover and a stop rate of 16.23%, with its secondary-market offer yield subsequently settling 18bps lower at 16.05%. Secondary OMO trading was mixed, although the March bill compressed by 5bps on Friday. System liquidity peaked at c.₦8.84tn on Tuesday before easing to close at c.₦4.86tn, below Monday’s c.₦6.45tn.
Nigerian Equities:
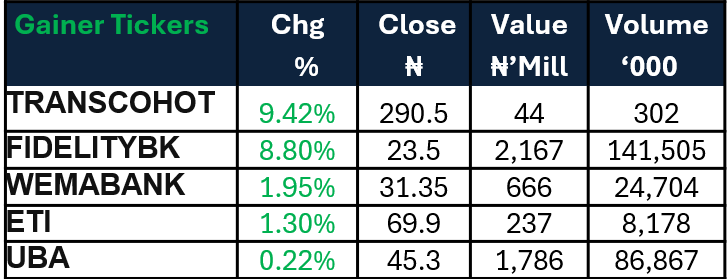
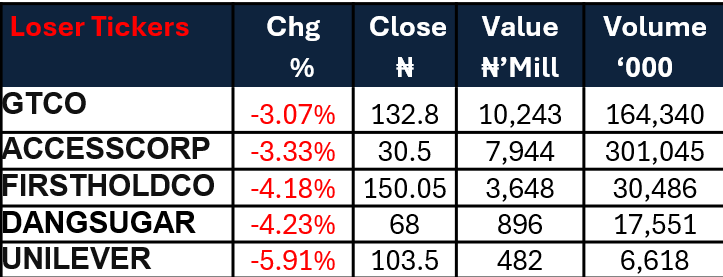
The ASI declined 0.52%,snapping three consecutive weeks of gains as selling pressure in heavyweight counters weighed on the market. Banking (-1.33%) and Food & Beverage (-0.91%) led losses, while Insurance (+0.61%) and Oil & Gas (+0.05%) bucked the trend,weakness in MTNN, FIRSTHOLDCO and GTCO dragged the broader index.
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 16.00 | 16.45 | (45) |
| Jun-32 | 16.06 | 16.45 | (39) |
| May-33 | 16.05 | 16.45 | (40) |
| Jul-34 | 16.10 | 16.45 | (35) |
| Jan-35 | 16.10 | 16.40 | (30) |
| Sep-36 | 16.10 | 16.45 | (35) |
| Apr-37 | 16.10 | 16.45 | (35) |
| Jun-38 | 16.11 | 16.45 | (34) |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 23-Sep-27 | 15.45 | 15.45 | 18.16 |
| 22-Jun-27 | 16.65 | 16.70 | 18.12 |
| 30-Mar-27 | 16.10 | 16.05 | 18.16 |
Indices Watch 1-Yr Performance %
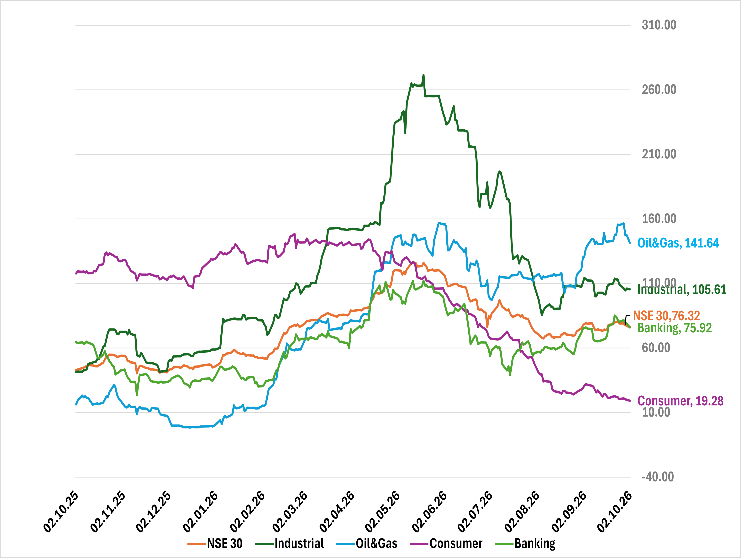
NSE 30 : Gainers and Losers
The Week Ahead…
The week opens with no scheduled auctions or key domestic macroeconomic releases. Inflows of c.₦2.9tn are expected from OMO and NTB maturities. The liquidity surplus should support demand, while possible NTB and OMO auctions and the anticipated release of the Q4 issuance calendar will guide market direction.
For equities, we expect selective two-way trading to persist as investors reassess valuations following September’s rally and position for the approaching Q3 earnings season. Improved market breadth may provide some support, although renewed demand in heavyweight names will be key to a broader recovery.