Fixed Income in Focus:
The fixed-income market maintained a broadly bullish bias, supported by ample liquidity, which peaked at ₦9.35tn before closing at ₦7.37tn. Bond demand centered on the mid-tenors, with average mid-yields across the quoted 2031s–2038s declining by c.▼9bps from Monday’s opening levels. In Treasury bills, early buying interest favored the long end, driving the 14-Oct-2027 bill lower by ▼25bps over the same period.
Wednesday’s NTB auction attracted strong demand, although secondary-market activity remained subdued thereafter, with yields largely unchanged through Friday. OMO trading was more mixed, as April maturities faced intermittent selling pressure. Thursday’s OMO auction drew strong subscriptions, but the immediate secondary-market response was muted. Renewed buying on Friday subsequently drove April OMO yields lower by c.▼10bps, partly reversing earlier weakness.
Nigerian Equities:
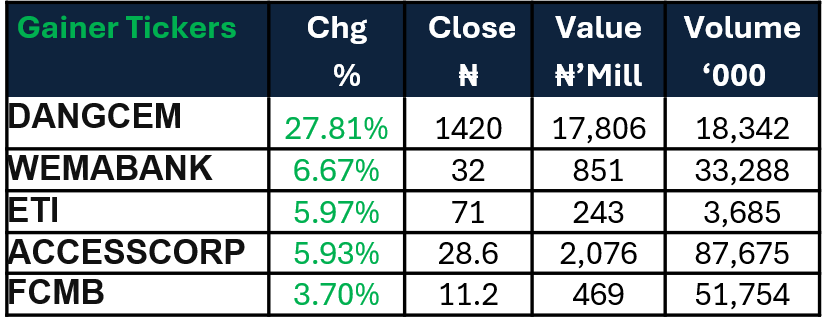
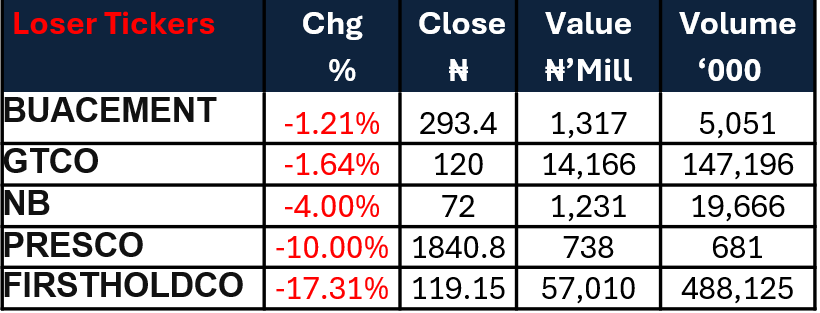
The ASI rebounded 2.86% WoW, snapping four consecutive weeks of losses as a sharp rally in Industrials (+14.58%) lifted the broader market. However, Banking (-3.42%) and Insurance (-2.13%) remained under pressure, highlighting a narrow, heavyweight-driven recovery rather than broad-based buying.
NTB Auction Result:
| 91-day | 182-day | 364-day | |
| Sales (₦‘bn) | 22.33 | 10.45 | 38.38 |
| Stop Rates | 15.40% | 15.79% | 15.80% |
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 16.85 | 16.75 | 10 |
| Jun-32 | 16.85 | 16.75 | 10 |
| May-33 | 16.85 | 16.80 | 5 |
| Jul-34 | 17.00 | 16.95 | 5 |
| Jan-35 | 17.00 | 16.90 | 10 |
| Sep-36 | 17.05 | 16.90 | 15 |
| Apr-37 | 17.05 | 16.95 | 10 |
| Jun-38 | 17.05 | 16.95 | 10 |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 14-Oct-27 | 15.65 | 15.40 | 18.04 |
| 20-Apr-27 | 17.05 | 17.00 | 18.33 |
| 06-Apr-27 | 16.85 | 17.10 | 18.58 |
Indices Watch 1-Yr Performance %
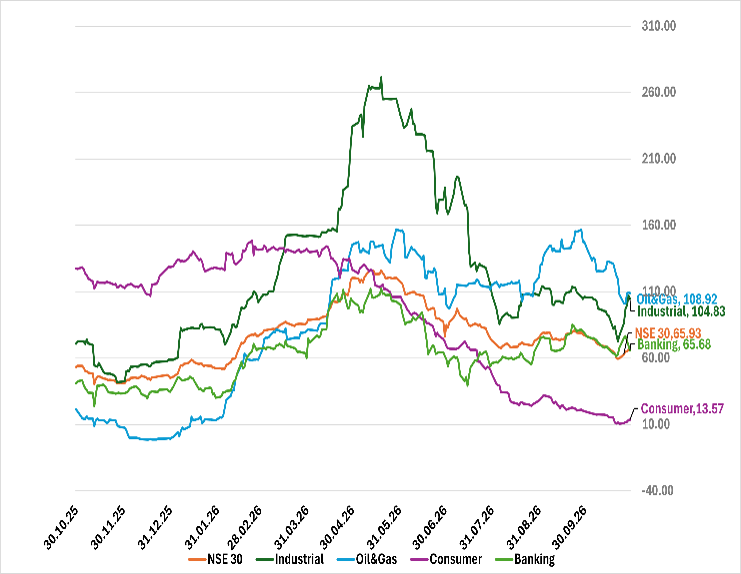
NSE 30 : Gainers and Losers
The Week Ahead…
Looking ahead, focus will be on the midweek NTB auction, where the DMO plans to offer ₦800bn, alongside expected inflows of c.₦2.59tn from NTB and OMO maturities. The liquidity boost should support demand, although the CBN may conduct an OMO auction to absorb excess funds. The auction outcome should set the tone for trading through the rest of the week, with global market developments also shaping sentiment.
For equities, we expect selective rotation into undervalued banks as investors assess the sustainability of the industrial-led rally. With the Dangote Refinery IPO closed, Q3 earnings and institutional flows could drive broader market participation.