Fixed Income in Focus:
The fixed-income market traded bullish during the week, supported by the MPC’s 350bps rate cut to 23.00%, auction demand and elevated liquidity. Bond yields compressed by c.60–75bps WoW across the 2031–2038 maturities, although profit-taking triggered a retracement later in the week. NTBs followed suit, with the 9-Sep-27 bill closing at 15.75%/15.60%, c.90–95bps lower WoW. At the auction, subscriptions totalled ₦4.23tn against a ₦497.58bn allotment, translating to a bid-to-cover ratio of 8.5x, while stop rates settled at 15.50%, 15.80% and 15.89%.
Similarly, OMO bills rallied for most of the week before yields backed up on Friday. The OMO auction attracted ₦6.09tn in subscriptions, with ₦2.25tn allotted across the 152- and 180-day papers at 17.29% and 16.99%. The 68-day paper recorded no sale, while the new 23-Mar-27 bill traded at 16.75%/16.65%. System liquidity climbed from ₦3.99tn to a peak of ₦7.45tn before closing at ₦5.98tn.
Nigerian Equities:
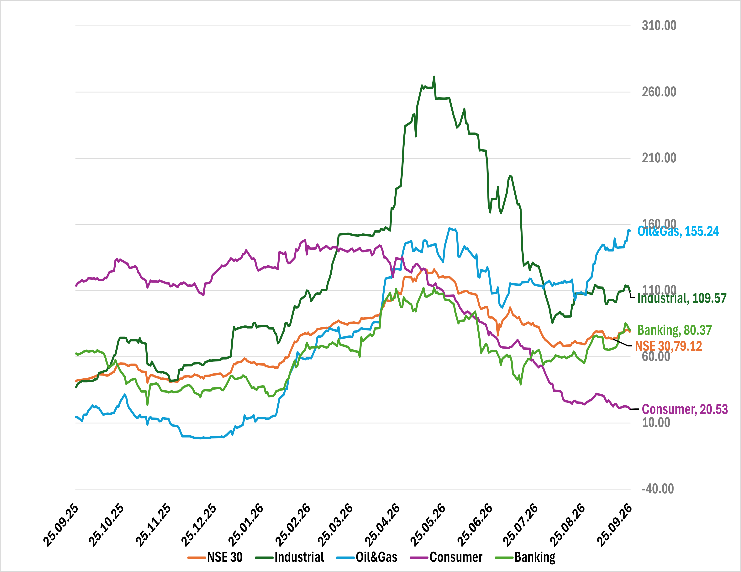
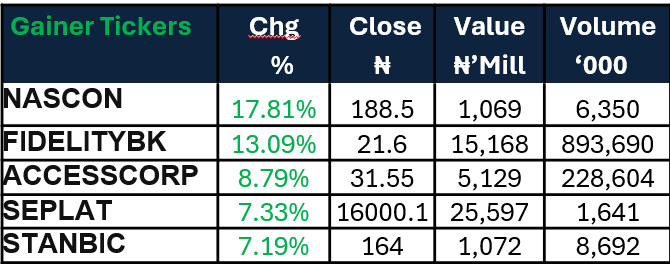
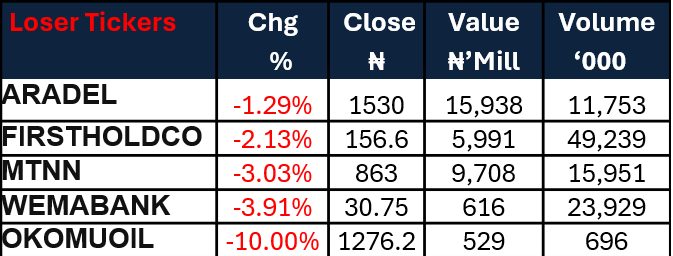
The ASI advanced 0.92% WoW, extending gains for a third consecutive week as buying interest remained firm across key sectors. Oil & Gas (+3.49%) and Banking (+3.06%) led gains, supported by demand for SEPLAT, GTCO and ZENITHBANK, while Insurance (-0.52%) was the only major sector to close lower.
NTB Auction Result:
| 91-day | 182-day | 364-day | |
| Sales (₦‘bn) | 11.027 | 39.485 | 447.071 |
| Stop Rates | 15.50% | 15.80% | 15.89% |
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 16.70 | 16.00 | 70 |
| Jun-32 | 16.70 | 16.06 | 64 |
| May-33 | 16.80 | 16.05 | 75 |
| Jul-34 | 16.85 | 16.10 | 75 |
| Jan-35 | 16.70 | 16.10 | 60 |
| Sep-36 | 16.70 | 16.10 | 60 |
| Apr-37 | 16.75 | 16.10 | 65 |
| Jun-38 | 16.80 | 16.11 | 69 |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 23-Sep-27 | 15.39 | 15.45 | 18.24 |
| 9-Sep-27 | 16.55 | 15.60 | 18.32 |
| 23-Mar-27 | 16.50 | 16.65 | 18.11 |
Indices Watch 1-Yr Performance %
NSE 30 : Gainers and Losers
The Week Ahead…
The week opens with no key domestic macroeconomic releases or scheduled auctions. Inflows of c.₦2.60tn are expected from OMO maturities and coupon payments on the 12.50% Mar-2035 and 12.98% Mar-2050 FGN bonds. Given the liquidity surplus, the CBN may conduct an OMO auction. Market direction will hinge on the extent of any liquidity mop-up, with excess liquidity supporting demand, although lower yields may sustain profit-taking.
The week opens with no key domestic macroeconomic releases or scheduled auctions. Inflows of c.₦2.60tn are expected from OMO maturities and coupon payments on the 12.50% Mar-2035 and 12.98% Mar-2050 FGN bonds. Given the liquidity surplus, the CBN may conduct an OMO auction. Market direction will hinge on the extent of any liquidity mop-up, with excess liquidity supporting demand, although lower yields may sustain profit-taking.