Fixed Income in Focus:
The fixed-income market traded mixed through the week, driven by the FGN bond auction, August inflation data and liquidity conditions. Bonds opened bullish before profit-taking and post-auction repricing weakened sentiment midweek. Renewed demand on Friday left the curve mixed WoW: the 2031s–2032s compressed by c.5bps, the 2033s–2034s rose by c.5bps, while the longer-dated 2035s–2038s declined by c.20–25bps. At the auction, the DMO allotted ₦748.64bn across the new 16.79% Sep-2036 and reopened 15.45% Jun-2038 bonds at stop rates of 16.79% and 16.85%, respectively, from ₦1.49tn in subscriptions. August headline inflation eased marginally to 15.39% YoY, supporting sentiment late in the week.
NTB activity remained muted, with yields largely unchanged, while OMO trading was active following Wednesday’s auction. System liquidity peaked at ₦5.89tn midweek before moderating to ₦2.50tn at Friday’s close.
Nigerian Equities:
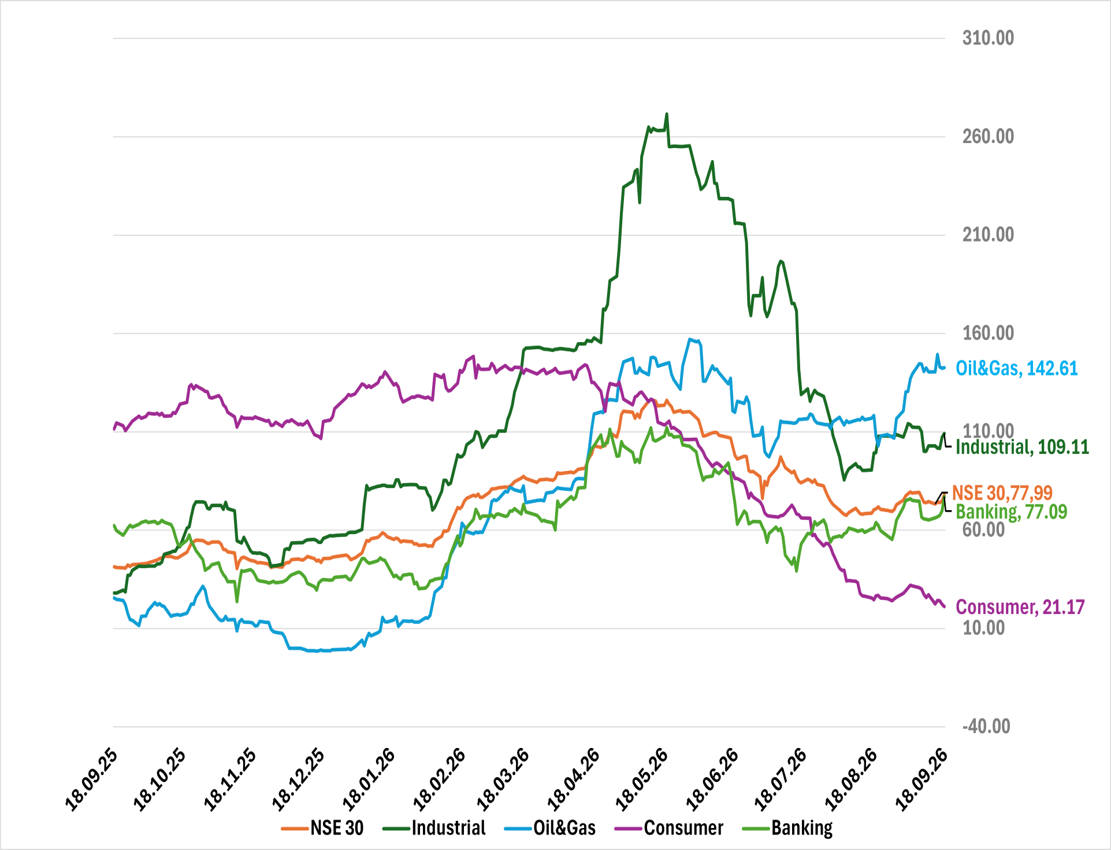
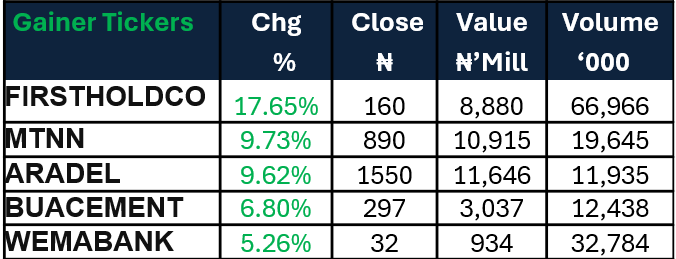
The ASI advanced 2.78% WoW, recovering the previous week’s losses as buying interest strengthened across sectors. Banking (+4.43%) led gains, followed by Insurance (+3.79%) and Oil & Gas (+3.71%), with renewed demand for large-cap names including FIRSTHOLDCO, MTNN and ARADEL supporting the rally.
Bond Auction Result:
| 16.79% Sep 36s | 15.45% Jun 38s | |
| Sales (₦‘bn) | 288.632 | 460.005 |
| Stop Rates | 16.79% | 16.85% |
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 16.75 | 16.70 | 5 |
| May-33 | 16.75 | 16.80 | (5) |
| Jul-34 | 16.80 | 16.85 | (5) |
| Jan-35 | 16.95 | 16.70 | 25 |
| Sep-36 | 16.95 | 16.70 | 25 |
| Apr-37 | 16.95 | 16.75 | 20 |
| Jun-38 | 17.05 | 16.80 | 25 |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 9-Sep-27 | 16.60 | 16.55 | 19.71 |
| 2-Sep-27 | 16.50 | 16.50 | 19.57 |
| 16-Feb-26 | 18.15 | 18.25 | 19.72 |
Indices Watch 1-Yr Performance %
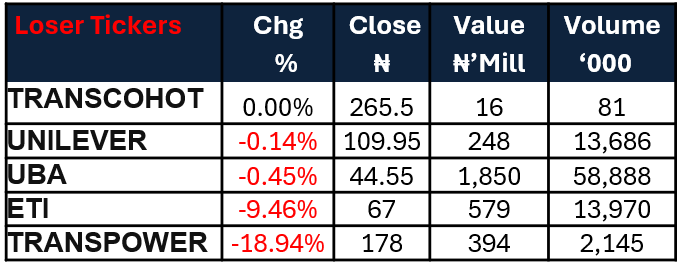
NSE 30 : Gainers and Losers
The Week Ahead…
Looking ahead, market direction will be shaped by the 307th MPC meeting and scheduled NTB auction, where the DMO plans to offer ₦500bn across the three tenors. This comes against net inflows of c.₦2.5tn from NTB and OMO maturities, alongside coupon payments on the 19.94% Mar 2027 and 21.00% Mar 2028 bonds. Activity should initially hinge on the MPC decision, with the auction outcome subsequently guiding rates and market sentiment.
For equities, We expect the MPC meeting and Nigeria’s FTSE Frontier Market re-entry to shape positioning, with the moderation in August inflation to 15.39% also informing rate expectations. Recent broad-based gains should remain supportive, although selective profit-taking may emerge.