Fixed Income in Focus:
The fixed-income market opened quietly on Monday before post-auction demand supported bond yield compression, following ₦1.75tn in subscriptions and ₦1.21tn in allotments at the FGN auction. Buying strengthened on Tuesday as liquidity rose to ₦7.74tn, supporting bonds and OMO bills, while the 14-Oct-2027 Treasury bill yield rose. The bullish trend continued on Wednesday, with Treasury bills largely stable. However, sentiment reversed late on Thursday following the CBN’s OMO auction announcement, triggering a sell-off despite liquidity peaking at ₦8.39tn.
The auction attracted ₦2.73tn in subscriptions, with ₦2.63tn allotted at stop rates of 17.63% and 17.14% for the 132-day and 180-day tenors, respectively. Friday saw further yield increases across bonds and the newly issued April OMO bill, while Treasury bills held steady. Despite the reversal, the 2031s–2033s retained c.▼18bps of compression over the week, with liquidity closing at ₦6.94tn.
Nigerian Equities:
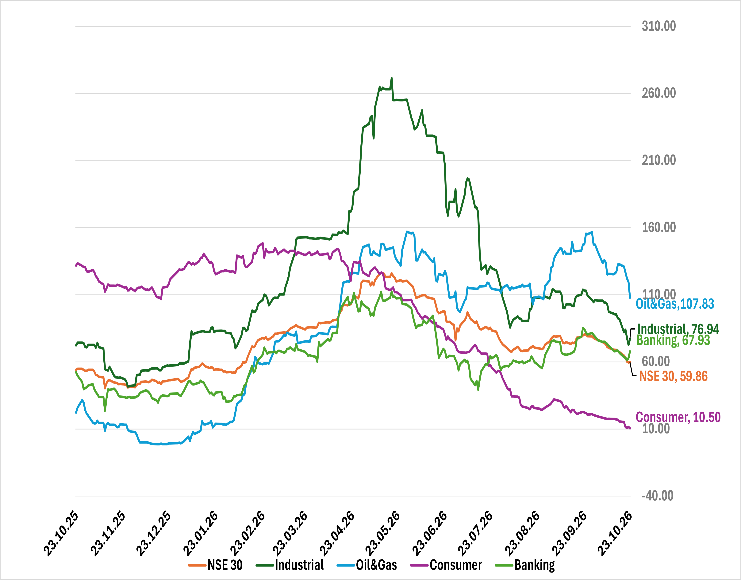
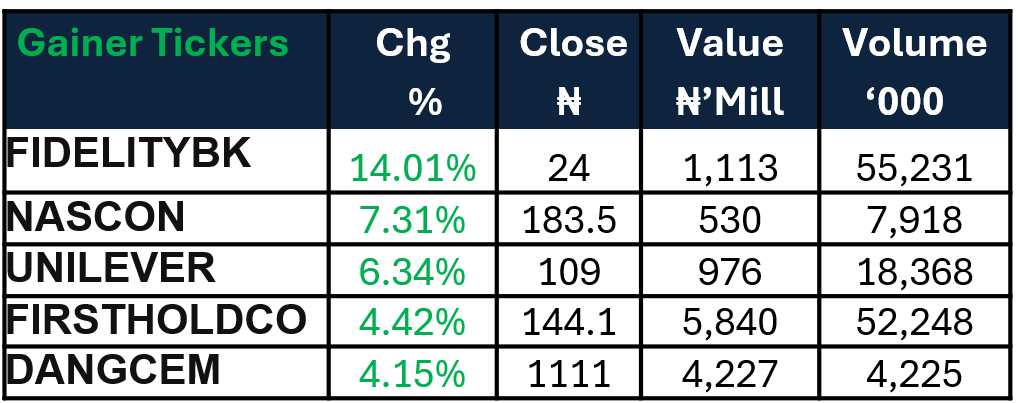
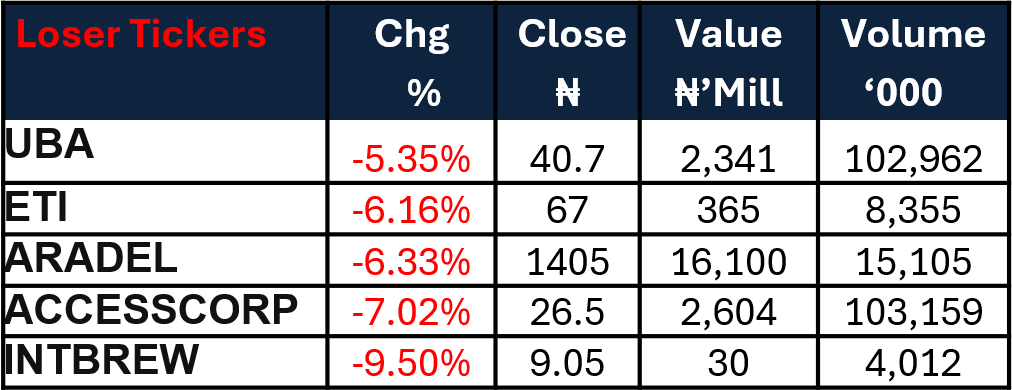
The ASI declined 0.13% WoW, extending its losing streak to four consecutive weeks amid continued weakness across key sectors. Insurance (-2.79%) and Oil & Gas (-2.55%) led losses, while Industrials (+1.95%) bucked the trend, supported by gains in DANGCEM.
Bond Auction Result:
| Feb 2034s | Sep 2036s | Jun 2038s | |
| Sales (₦‘bn) | 19.521 | 29.544 | 219.996 |
| Stop Rates | 16.99% | 17.29% | 17.19% |
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 17.00 | 16.80 | 20 |
| Jun-32 | 17.00 | 16.80 | 20 |
| May-33 | 17.00 | 16.80 | 20 |
| Jul-34 | 17.05 | 16.95 | 10 |
| Jan-35 | 17.05 | 17.00 | 5 |
| Sep-36 | 17.05 | 17.05 | – |
| Apr-37 | 17.05 | 17.05 | – |
| Jun-38 | 17.05 | 17.05 | – |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 14-Oct-27 | 15.60 | 15.65 | 18.46 |
| 20-Apr-27 | 16.90 | 16.85 | 18.01 |
| 06-Apr-27 | – | 17.05 | 18.35 |
Indices Watch 1-Yr Performance %
NSE 30 : Gainers and Losers
The Week Ahead…
Focus will be on Wednesday’s ₦800bn NTB auction across three tenors, against expected inflows of c.₦2.52tn from OMO/NTB maturities and coupons on the FGN 14.55% Apr 2029s, 12.50% Apr 2032s and 14.80% Apr 2049s. The inflows should support demand, while auction settlement and fresh OMO issuance could absorb excess liquidity. Global macroeconomic developments, geopolitical factors and the auction outcome will shape the week’s trading tone.
For equities, we expect the Dangote Refinery IPO’s closing and upcoming Q3 earnings to shape positioning, particularly in banking and industrials. The offer’s conclusion could ease liquidity pressures, while earnings will be key to a sustained recovery.