
Fixed Income in Focus:
The fixed-income market was volatile this week, as auction flows and tightening liquidity set the tone across all segments. Bonds opened quietly before rallying on the revision of tenors in the bond auction circular, with yields on the 2032s–2038s compressing by c.▼18bps. The rally, however, lacked follow-through, as profit-taking emerged after the CBN’s OMO auction mopped up c.₦3.85tn.
This left average mid-yields across the 2031s–2038s broadly unchanged for the week, although the curve flattened as the short end backed up while the mid-to-long tenors held modest gains. The liquidity squeeze carried into the NTB auction, where the 1-year stop rate rose 9bps to 15.89% at a 1.57x bid-to-cover ratio. The new 11-Nov-2027 bill later found renewed demand to close at 15.85/15.75%. Meanwhile, OMO yields drifted higher in the secondary market, and the 05-Oct-2027 paper, issued at a 17.44% stop rate, closed the week at 16.00/15.85%. Reported liquidity closed at c.₦3.97tn, down from c.₦6.09tn at the start of the week
Nigerian Equities:
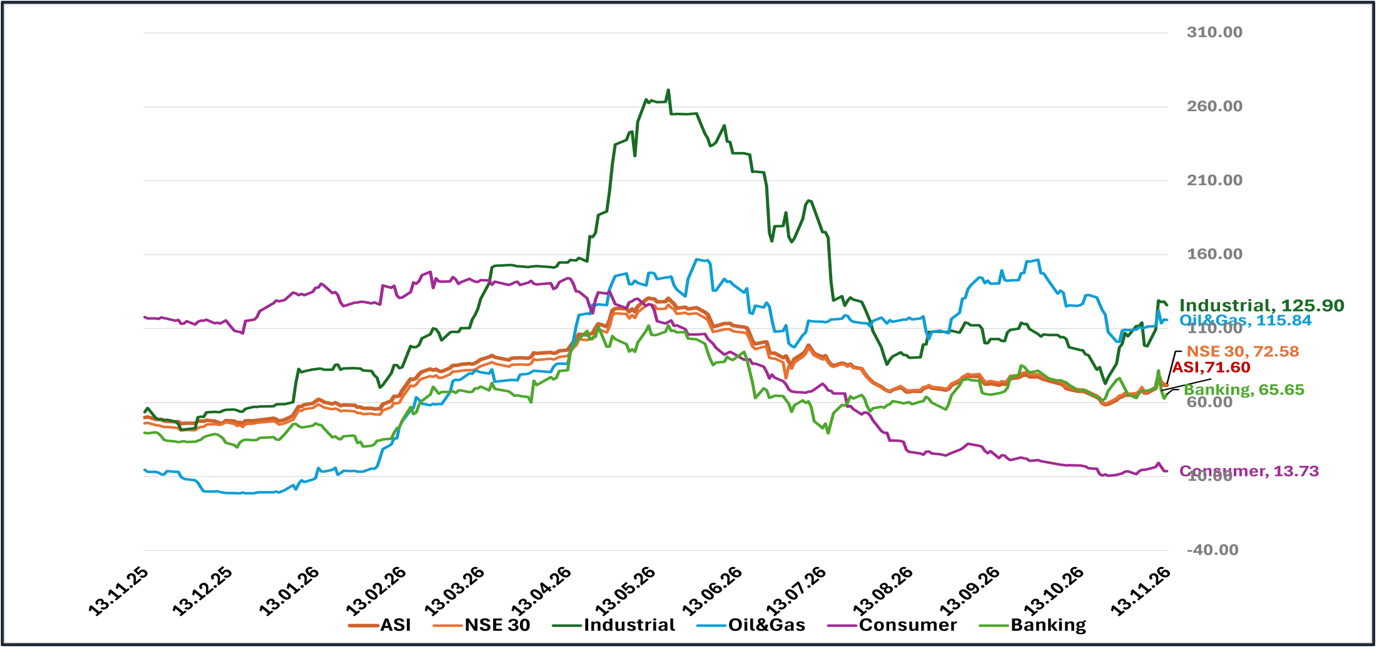
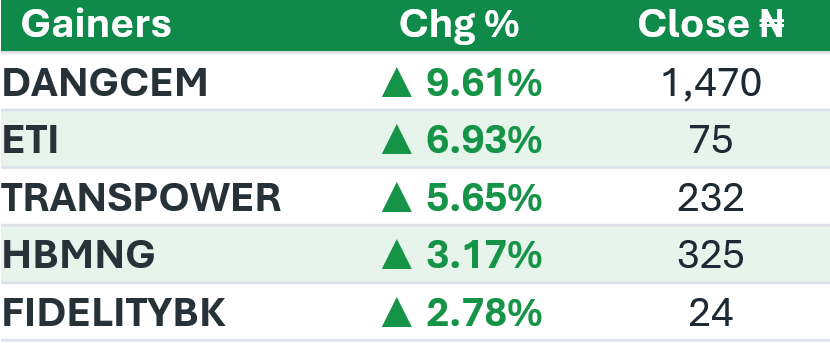
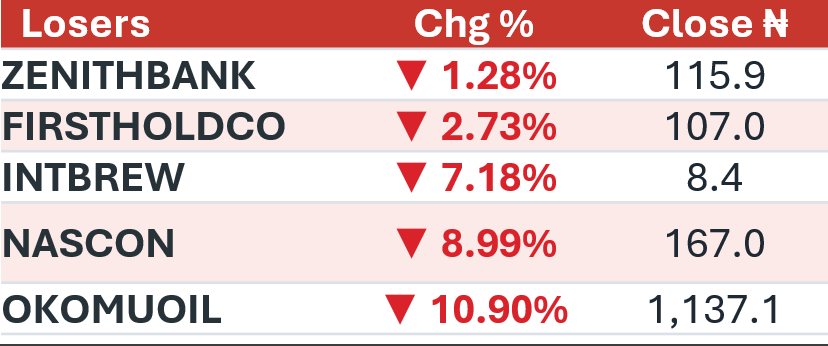
The ASI rebounded 1.36% WoW, recovering part of the previous week’s losses as renewed buying in DANGCEM drove an industrial-led recovery. Industrials (+6.11%) and Insurance (+4.44%) led gains, while Banking (-0.21%) and Food & Beverage (-0.55%) lagged, highlighting continued sector divergence despite improved market breadth.
NTB Auction Result:
| 91-day | 182-day | 364-day | |
| Sales (₦‘bn) | 18.120 | 22.282 | 1,079.100 |
| Stop Rates | 15.40% | 15.79% | 15.89% |
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 16.50 | 16.70 | (20) |
| Jun-32 | 16.65 | 16.70 | (5) |
| May-33 | 16.75 | 16.77 | (5) |
| Jul-34 | 16.75 | 16.70 | 5 |
| Jan-35 | 16.75 | 16.65 | 10 |
| Sep-36 | 16.75 | 16.70 | 5 |
| Apr-37 | 16.75 | 16.63 | 12 |
| Jun-38 | 16.75 | 16.75 | – |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 11-Nov-27 | 15.75 | 15.75 | 18.65 |
| 2-Nov-27 | 15.50 | 15.65 | 18.42 |
| 05-Oct-27 | 15.65 | 15.85 | 18.44 |
Indices Watch 1-Yr Performance %
NSE 30 : Gainers and Losers
The Week Ahead…
The week opens with a scheduled ₦2tn bond auction across the 21.00% Mar 2028s, 19.30% Apr 2029s, 17.945% Aug 2030s and 19.89% May 2033s. This supply is set against c.₦3.61tn in expected inflows from NTB and OMO maturities and coupons on the 19.89% May 2033s, 16.956% May 2032s and 8.50% Nov 2029s. With October CPI also due, the auction outcome and inflation data will determine market activity for the rest of the week.
For equities, we favour selective accumulation in quality banking names following sustained weakness, while watching for broader participation beyond DANGCEM. October inflation data, due 16 November, and recent naira weakness could influence investor sentiment and sector positioning.