Fixed Income in Focus:
The fixed-income market traded on a bullish note during the week, with buying interest seen across the FGN Bonds, NTB and OMO segments. In the Bonds market, demand was concentrated on the highest yielding paper, Jun-38s compressing it 70bps WoW to close at 16.60%, while the Apr-37s declined by 55bps other maturities around the belly of the curve closed 40–45bps lower.
In the NTB market, attention shifted to the newly issued 2-Sep-27 paper following Wednesday’s auction. The 364-day bill attracted ₦3.24tn in subscriptions, recording a 4.25x bid-to-cover ratio, while its stop rate declined by 31bps to 16.84%. Post-auction demand pushed the new bill further down to 16.45% in the secondary market. OMO activity remained firm, centred on the 26-Jan-27 and 2-Feb-27 papers, with the 26-Jan-27 compressing by 45bps WoW to 18.30%. System liquidity closed almost unchanged at c.₦4.66tn.
Nigerian Equities:
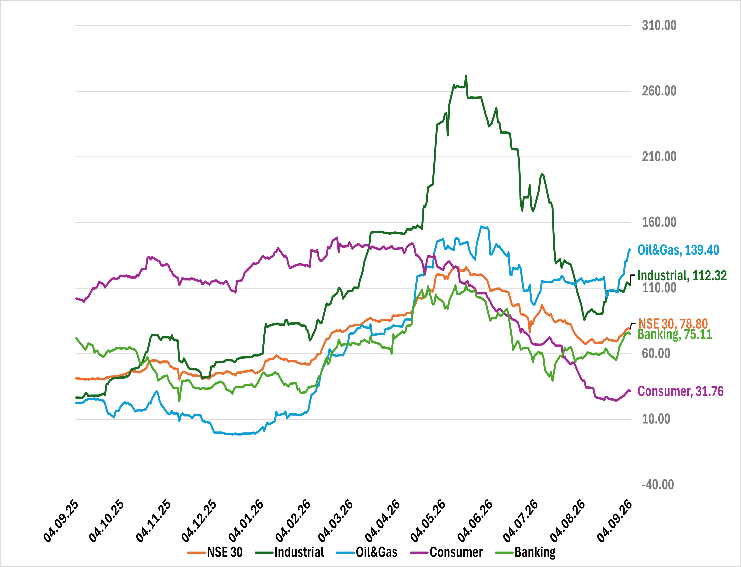
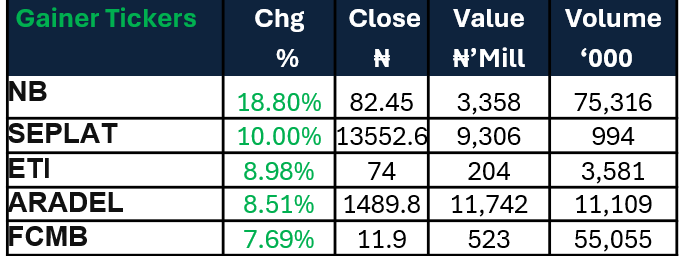
The ASI advanced 2.36% WoW, extending its recovery as stronger activity reinforced positive sentiment. Oil & Gas (+9.10%) led gains on strong demand for SEPLAT, OANDO and ARADEL, while Banking (+3.58%) also strengthened. FTSE-related positioning provided an additional boost, with interest increasingly concentrated around eligible counters ahead of Nigeria’s Frontier Market return.
NTB Auction Result:
| 91-day | 182-day | 364-day | |
| Sales (₦‘bn) | 76.278 | 27.267 | 762.167 |
| Stop Rates | 16.30% | 16.50% | 16.84% |
FI Weekly Snapshot
| FGN Bond | Open (Yield) | Close (Yield) | Chg WoW |
| % | % | (Bps) | |
| Feb-31 | 17.05 | 16.65 | 40 |
| May-33 | 17.10 | 16.65 | 45 |
| Feb-34 | 17.05 | 16.65 | 40 |
| Jan-35 | 17.10 | 16.70 | 40 |
| Apr-37 | 17.20 | 16.65 | 55 |
| Jun-38 | 17.30 | 16.60 | 70 |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 2-Sep-27 | 16.84 | 16.45 | 19.64 |
| 29-Jul-27 | 16.85 | 16.80 | 19.76 |
| 26-Jan-27 | 18.75 | 18.30 | 19.69 |
Indices Watch 1-Yr Performance %
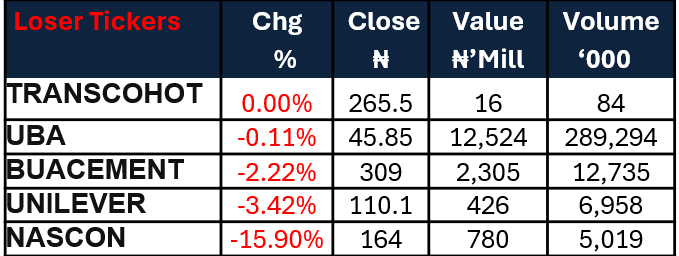
NSE 30 : Gainers and Losers
The Week Ahead…
The new week opens with a ₦1.2 trillion OMO maturity supporting system liquidity, keeping attention on any CBN liquidity-management action. In the NTB market, the ₦500 billion auction scheduled for Wednesday should set the tone, while the newly issued 2-Sep-27 paper may remain active in the secondary market. Bond activity should remain focused on the 2035s, 2037s and 2038s, although some profit-taking may occur. OMO trading is expected to remain centered on the January and February maturities.
For equities,we expect FTSE-related positioning to remain a market driver, while attention may increasingly shift toward the Dangote Refinery IPO ahead of its expected 14 September opening. Improved breadth should remain supportive, despite potential profit-taking.