
Fixed Income in Focus:
The fixed-income market opened on a bullish note, with ample liquidity supporting demand for the 2031s–2038s. Buying interest persisted through midweek, while Treasury bill activity remained subdued ahead of Wednesday’s NTB auction. The auction recorded strong demand at a bid-to-cover ratio of 4.01x, with stop rates unchanged across all tenors.
Post-auction demand supported the new 4-Nov-2027 bill, which closed the week at 15.60/15.50%. Meanwhile, Tuesday’s and Friday’s OMO auctions recorded bid-to-cover ratios of 1.19x and 2.11x, respectively. Friday’s demand centered on the 361-day paper, which cleared at 15.74% before closing at 15.70/15.50%. Mild profit-taking trimmed bond gains on Friday, although average mid-yields across the 2031s–2038s still compressed by c.▼16bps over the week. Reported liquidity stood at c.₦8.51tn, pending auction debits and intra-day adjustments, leaving a supportive backdrop for demand.
Nigerian Equities:
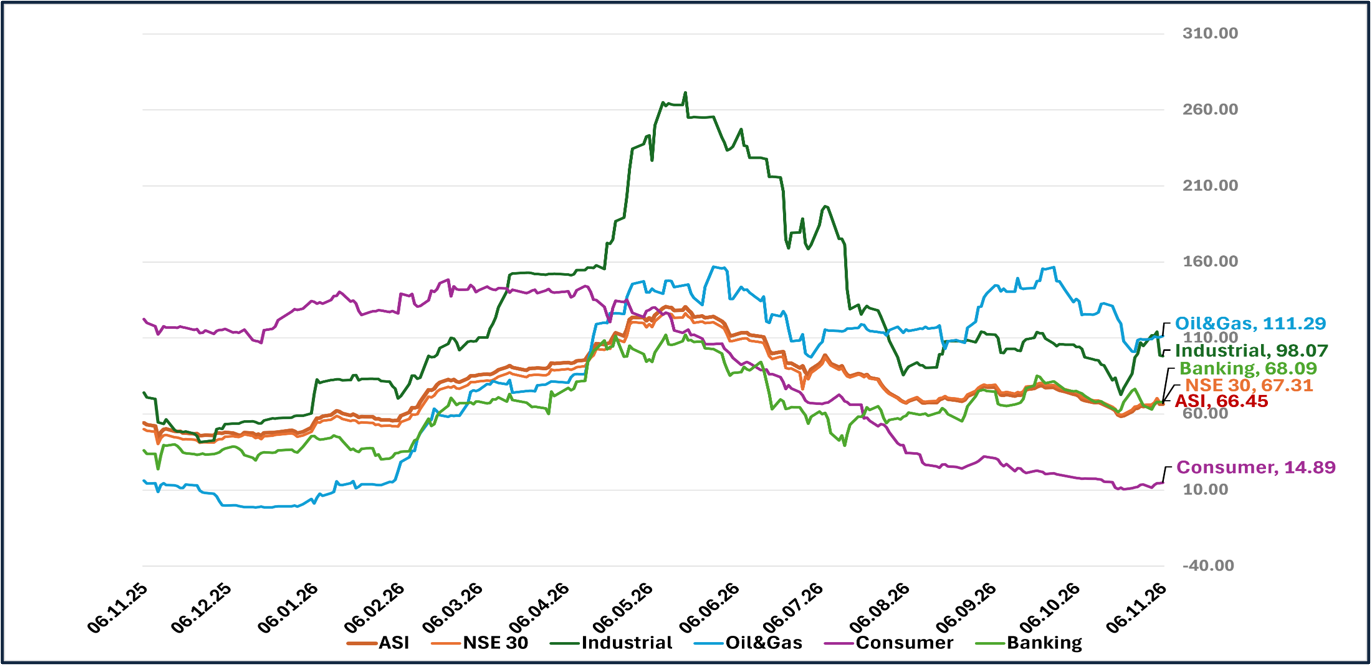
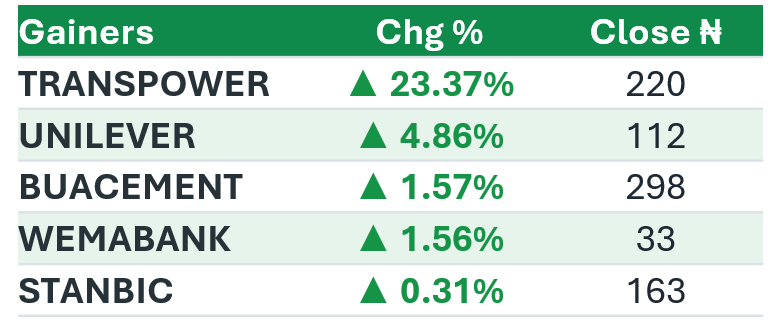
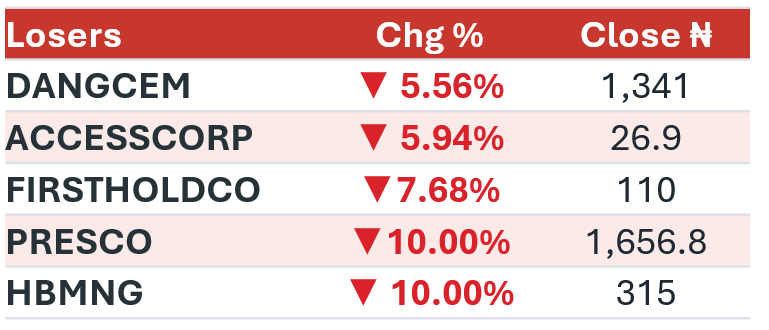
The ASI declined 2.13% WoW, reversing the previous week’s rally. Industrials (-4.35%) and Oil & Gas (-3.72%) led losses, driven by weakness in DANGCEM and ARADEL, while Banking (-2.45%) also retreated. The sell-off erased much of October’s late recovery, with declining turnover and weak breadth reflecting cautious positioning.
NTB Auction Result:
| 91-day | 182-day | 364-day | |
| Sales (₦‘bn) | 22.395 | 25.169 | 461.836 |
| Stop Rates | 15.40% | 15.79% | 15.80% |
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 16.75 | 16.6 | 10 |
| Jun-32 | 16.75 | 16.7 | 5 |
| May-33 | 16.8 | 16.75 | 5 |
| Jul-34 | 16.95 | 16.75 | 20 |
| Jan-35 | 16.9 | 16.75 | 15 |
| Sep-36 | 16.9 | 16.75 | 15 |
| Apr-37 | 16.95 | 16.75 | 20 |
| Jun-38 | 16.95 | 16.75 | 20 |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 4-Nov-27 | 15.6 | 15.5 | 18.31 |
| 2-Nov-27 | 15.5 | 15.5 | 18.29 |
| 16-Mar–27 | 17.45 | 17.5 | 18.64 |
Indices Watch 1-Yr Performance %
NSE 30 : Gainers and Losers
The Week Ahead…
The week opens ahead of Wednesday’s scheduled ₦800bn NTB auction, with c.₦2.45tn in expected NTB and OMO maturities supporting demand. Activity should center on positioning ahead of the auction and its outcome, particularly at the long end, although additional OMO issuance could temper yield compression.
For equities, We expect investors to reassess industrial heavyweights following the sharp correction, with selective entry opportunities emerging in oversold quality names.The remaining Q3 earnings releases could influence positioning, while a recovery will require renewed institutional demand.