Fixed Income in Focus:
The fixed-income market traded on a mixed note during the week, with mild bearishness in bonds offset by bullish activity across the NTB and OMO segments. In bonds, most benchmark yields rose by 5bps WoW, while the Jul-34s and Jun-35s were unchanged. The Jun-38s outperformed, compressing by 5bps to close at 17.30%. In the NTB market, longer-dated yields compressed by c.30–50bps WoW as the 17.15% stop rate on the new 364-day bill prompted a repricing of outstanding papers. The auction attracted strong demand, with the 364-day paper recording c.₦3.63tn in subscriptions, while the newly issued bill remained scarce on offer post-auction.
OMO activity remained bullish amid strong participation at back-to-back auctions, with the latter drawing c.₦4.36tn in subscriptions. Secondary-market demand remained firm, centred on the recently issued 26-Jan and 1-Dec papers. System liquidity remained firm, closing the week at c.₦3.61tn.
Nigerian Equities:
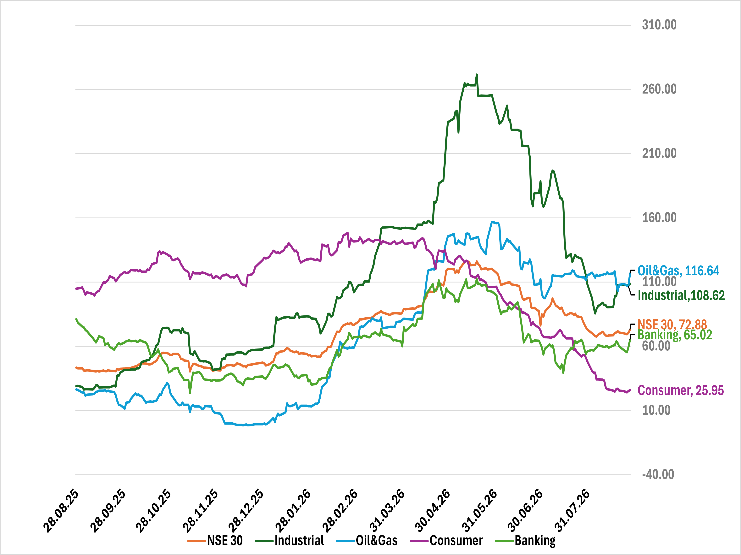
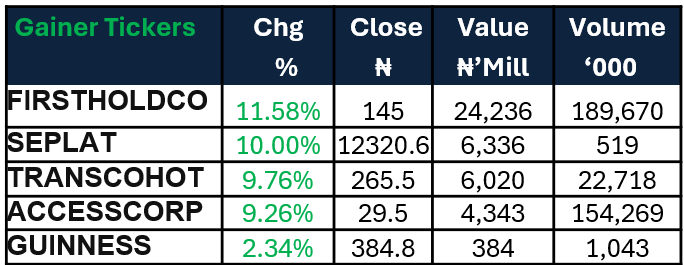
The ASI advanced 0.81% WoW, snapping the recent losing streak as sentiment improved following FTSE Russell’s confirmation of Nigeria’s return to Frontier Market status. Oil & Gas (+4.54%) and Banking (+2.89%) led the recovery, supported by strong gains in SEPLAT, FIRSTHOLDCO and ACCESSCORP, while Food & Beverage (-0.67%) remained subdued.
NTB Auction Result:
| 91-day | 182-day | 364-day | |
| Sales (₦‘bn) | 89.100 | 35.594 | 638.190 |
| Stop Rates | 16.30% | 16.50% | 17.15% |
FI Weekly Snapshot
| FGN Bond | Open (Yield) | Close (Yield) | Chg WoW |
| % | % | (Bps) | |
| Feb-31 | 17.00 | 17.05 | (5) |
| May-33 | 17.05 | 17.10 | (5) |
| Jul-34 | 17.05 | 17.05 | – |
| Jan-35 | 17.10 | 17.10 | – |
| Apr-37 | 17.15 | 17.20 | (5) |
| Jun-38 | 17.35 | 17.30 | 5 |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 12-Aug-27 | 17.15 | 16.85 | 20.06 |
| 29-Jul-27 | 17.30 | 16.75 | 19.77 |
| 26-Jan-26 | 19.00 | 18.80 | 20.36 |
Indices Watch 1-Yr Performance %
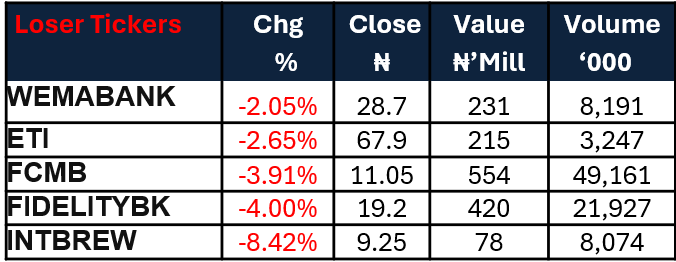
NSE 30 : Gainers and Losers
The Week Ahead…
The week opens ahead of a primary market Treasury bill auction scheduled for midweek, where the DMO plans to offer ₦700bn across the three tenors against ₦734.81bn in maturities. Liquidity is expected to receive further support from c.₦1.80tn in OMO maturities. Market activity will likely be shaped by the NTB auction outcome and any CBN OMO issuance to absorb the expected liquidity inflow.
For equities,we expect FTSE Frontier Market positioning to remain a key driver, with the 2 September indicative index files likely to sharpen focus on liquid, index-eligible names.This could support renewed foreign interest, though sustained upside will depend on broader participation beyond banking and energy.