Fixed Income in Focus:
The fixed-income market traded bearish through the week, led by sustained selling in bonds despite Friday’s recovery. Activity centred on the 2031s–2038s, where mid-yields rose by c.22bps over the week, with Thursday recording the sharpest sell-off. Treasury bills remained largely muted around Wednesday’s auction, where the 364-day bill attracted ₦1.68tn in subscriptions against ₦885bn allotted, clearing at 15.85%, ▼4bps.
Post-auction, the new 7-Oct-2027 benchmark settled at 15.80/15.75% and held through Friday. In OMO, Tuesday’s auction attracted ₦3.51tn in subscriptions, with ₦3.31tn allotted across the 147-day and 182-day bills at 17.22% and 16.92%, respectively. Secondary trading remained bearish overall despite late-week compression, with the June bill closing ▲10bps in mid-yield. Liquidity closed at c.₦3.71tn, down from c.₦5.05tn at the week’s opening, after peaking at c.₦7.09tn on Tuesday.
Nigerian Equities:
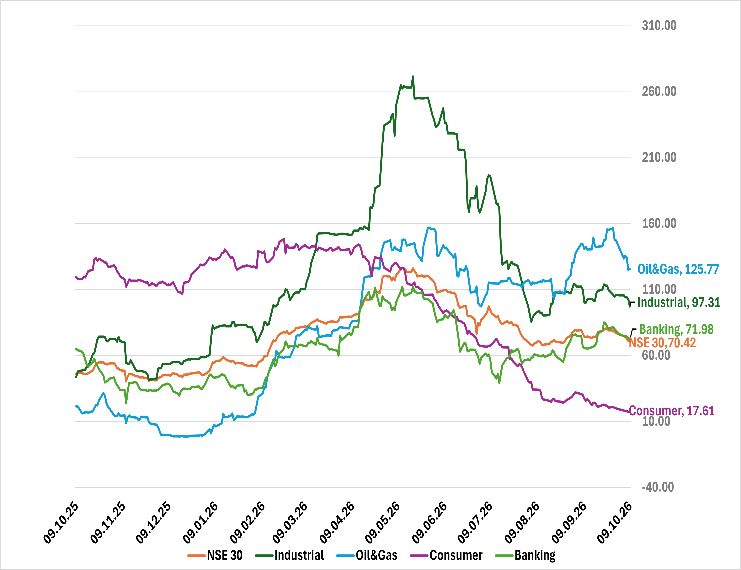
The ASI declined 0.97% WoW, extending the previous week’s losses as selling pressure persisted across key sectors. Oil & Gas (-3.85%) led declines, followed by Banking (-2.64%) and Insurance (-1.74%), while Industrials (+0.02%) remained relatively flat.
NTB Auction Result:
| 91-day | 182-day | 364-day | |
| Sales (₦‘bn) | 38.548 | 44.922 | 885.002 |
| Stop Rates | 15.50% | 15.80% | 15.85% |
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 16.45 | 16.65 | (20) |
| Jun-32 | 16.45 | 16.65 | (20) |
| May-33 | 16.45 | 16.65 | (20) |
| Jul-34 | 16.45 | 16.65 | (20) |
| Jan-35 | 16.40 | 16.70 | (30) |
| Sep-36 | 16.45 | 16.70 | (25) |
| Apr-37 | 16.45 | 16.70 | (25) |
| Jun-38 | 16.45 | 16.70 | (25) |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 07-Oct-27 | 15.75 | 15.75 | 18.66 |
| 22-Jun-27 | 16.05 | 16.15 | 18.19 |
| 06-Apr-26 | 16.80 | 17.10 | 18.65 |
Indices Watch 1-Yr Performance %
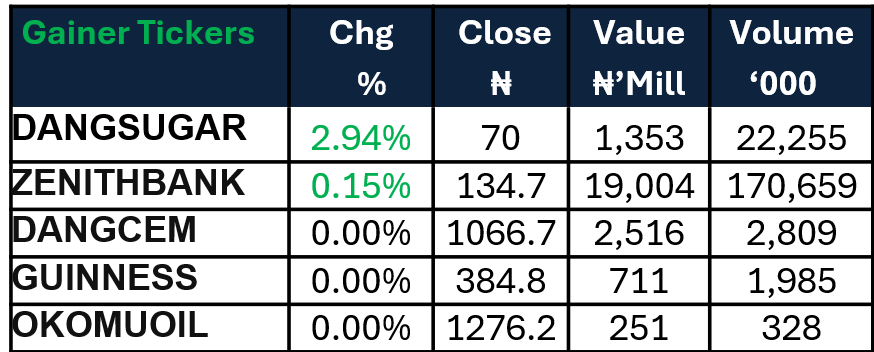
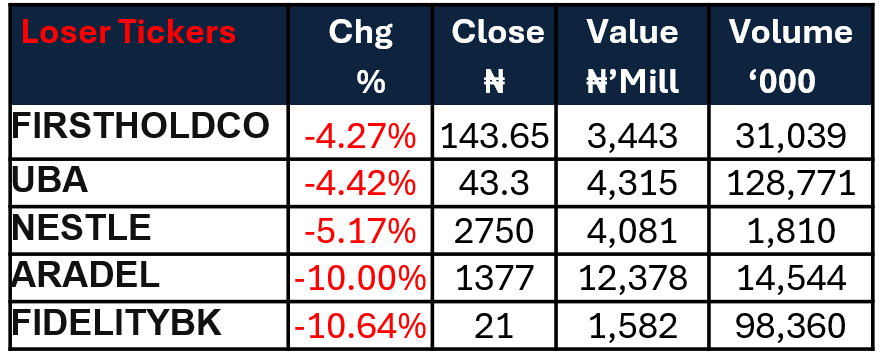
NSE 30 : Gainers and Losers
The Week Ahead…
Focus will be on the September CPI inflation report and expected net inflows of c.₦2.5tn from NTB and OMO maturities and the 19.30% Apr-2029 bond coupon. The liquidity boost should support demand, though the CBN may hold an OMO auction to absorb excess funds. Positioning ahead of the inflation release and its outcome should guide the week’s trading.
For equities, we expect selective bargain hunting after two consecutive weeks of losses, although weak breadth may limit the recovery. Focus will shift to September inflation and Q3 earnings, while the Dangote Refinery IPO closing on Tuesday, we could also see some sell-offs as investors make a last-minute dash to free up cash.