Fixed Income in Focus:
The fixed-income market traded mixed through the week,opening on a bullish note before sentiment weakened from Tuesday as yields backed up. In bonds, activity remained concentrated around the belly, with the 2031–2034 maturities still closing c.▼5–10bps below Monday’s opening levels despite the mid-week selloff, while the 2035–2038s closed c.▲15–25bps higher. Liquidity strengthened materially through the week, rising from c.₦2.53tn on Monday to c.₦4.08tn by Friday.
The NTB segment followed a similar pattern, with the longer-dated June and July bills bearing most of the selling pressure as the week progressed. From Monday’s opening levels, benchmark NTB yields closed c.▲5–15bps higher, with the 29-Jul-27 unchanged at 16.95%. OMO activity was supported by two CBN auctions during the week; notably, the 22-Dec bill cleared at 20.10% with a strong 8.41x bid-to-cover at Monday’s auction. Secondary activity remained relatively muted thereafter, with December OMO bills ending the week around 20.00% offer.
Nigerian Equities:
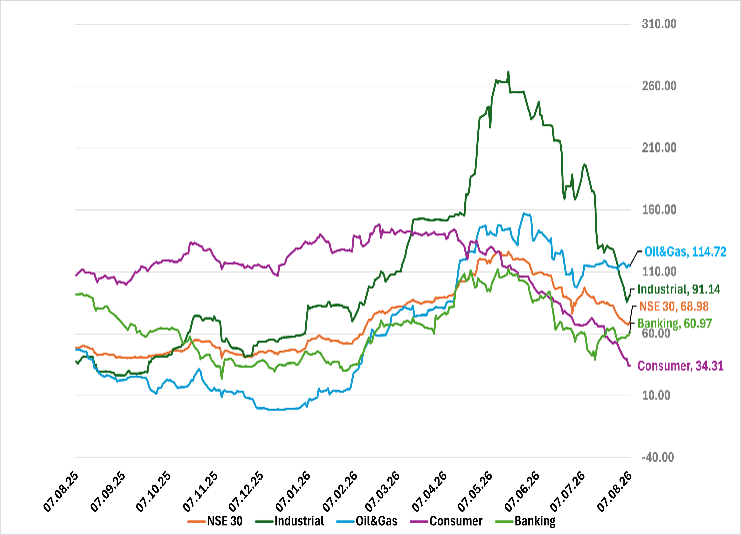
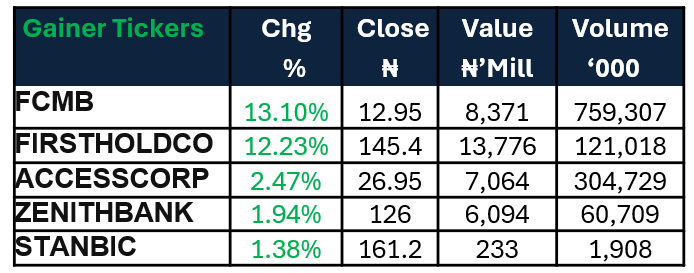
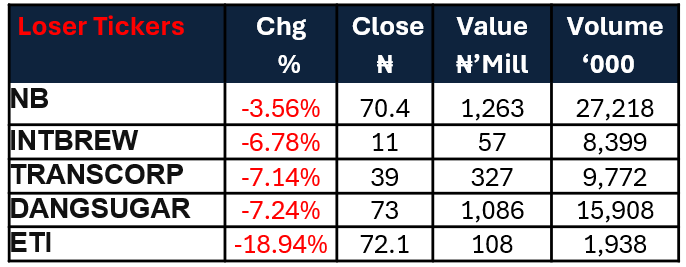
The ASI edged 0.12% higher WoW, with Banking (+2.33%) driving the positive close, while Insurance (-3.31%) and Food & Beverage (-1.75%) led losses. The muted index move masked stronger activity beneath the surface, with flows rotating into financial names while profit-taking persisted across select consumer and insurance counters.
FI Weekly Snapshot
| FGN Bond | Open (Yield) | Close (Yield) | Chg WoW |
| % | % | (Bps) | |
| Feb-31 | 17.15 | 17.10 | 5 |
| May-33 | 17.25 | 17.15 | 10 |
| Feb-34 | 17.25 | 17.20 | (5) |
| Jan-35 | 17.20 | 17.35 | (15) |
| Apr-37 | 17.20 | 17.35 | (15) |
| Jun-38 | 17.25 | 17.50 | (25) |
| NTB | Open | Close | Effective Yield |
| % | % | % | |
| 29-Jul-27 | 16.95 | 16.95 | 20.28 |
| 15-Jul-27 | 16.95 | 17.10 | 20.13 |
| 17-Jun-27 | 17.05 | 17.10 | 19.96 |
Indices Watch 1-Yr Performance %
NSE 30 : Gainers and Losers
The Week Ahead…
The week is set against a scheduled NTB auction, with the DMO expected to offer ₦700bn across the three maturities. Activity will be dictated by positioning ahead of the auction and its outcome, with a c.₦2.48tn OMO maturity supporting liquidity before the offer. However, the CBN could conduct an OMO auction to moderate liquidity.
For equities, We expect sector rotation to remain a key feature, as the market’s headline performance masks stronger moves within individual sectors. Following Banking’s recent outperformance, flows may rotate toward lagging quality names, with stock-specific catalysts likely to drive activity rather than a broad market rally.