Fixed Income in Focus:
The week opened bearish as the Q4 bond calendar signaled increased supply. Buying interest returned on Tuesday as liquidity rose to c. ₦6.49tn, supporting mid-tenor bonds and April and June OMOs. Sentiment softened ahead of Wednesday’s NTB auction, where robust demand drove an overall BTC of 3.84x, with ₦1.03tn subscribed against ₦269.06bn allotted. Interest centered on the 364-day bill, whose stop rate edged up ▲5bps to 15.90%. September’s headline inflation eased to 14.63% YoY from 15.39% in August, a 76bps decline, supporting renewed buying on Thursday.
Although bonds ended Friday slightly bearish ahead of the forthcoming auction. Offers across the 2031s–2038s closed an average ▲36bps above Monday’s opening levels. Bills finished firmer, with offers on the new 364-day NTB compressing ▼10bps post-auction to 15.60%, alongside renewed demand for the April OMO. Liquidity closed at c. ₦6.28tn, up from ₦4.04tn on Monday.
Nigerian Equities:
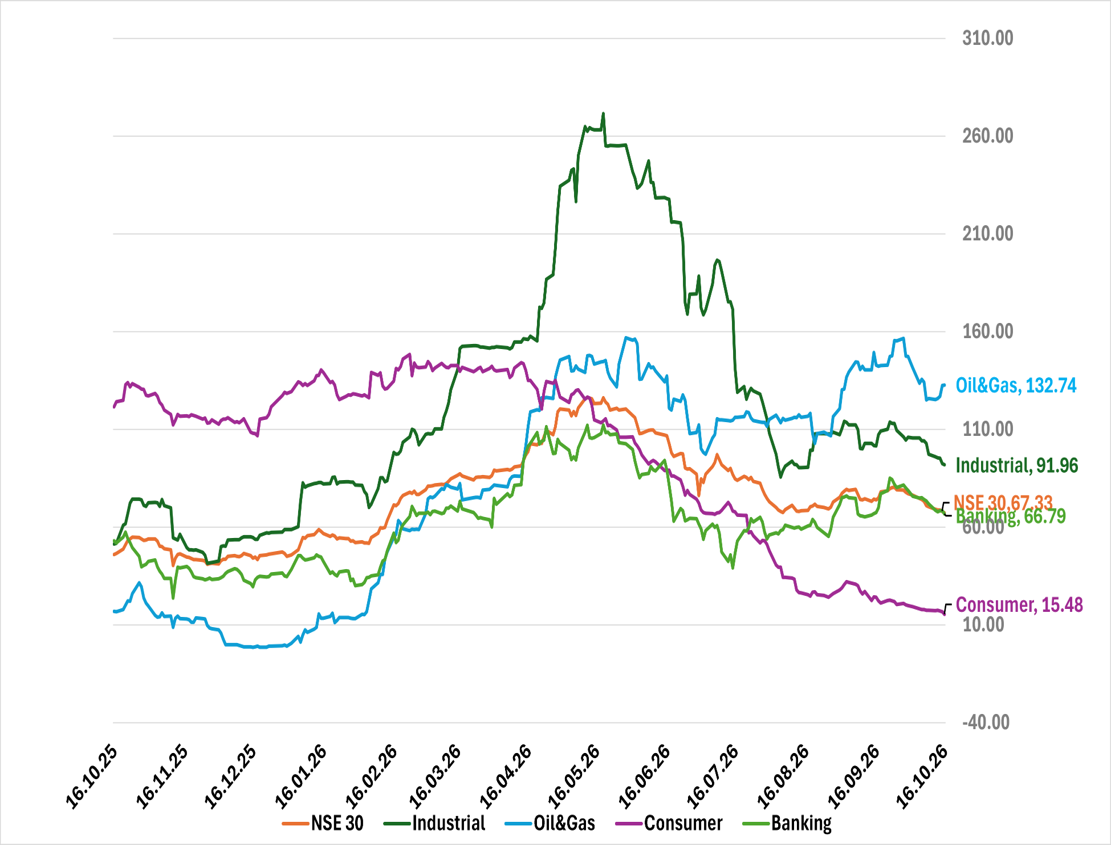
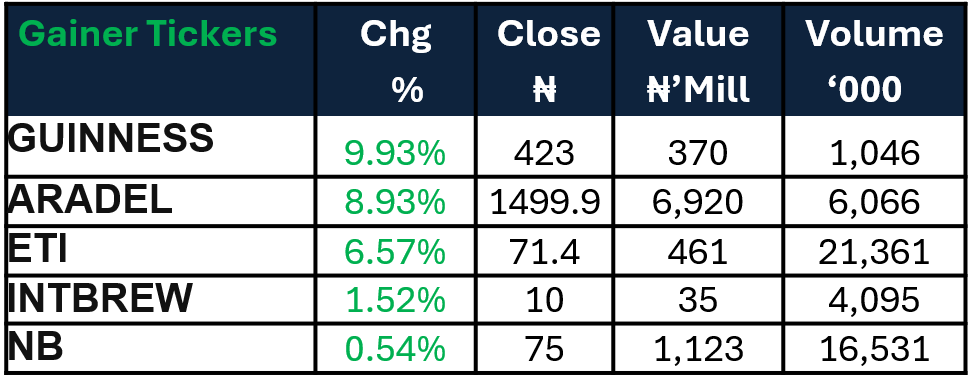
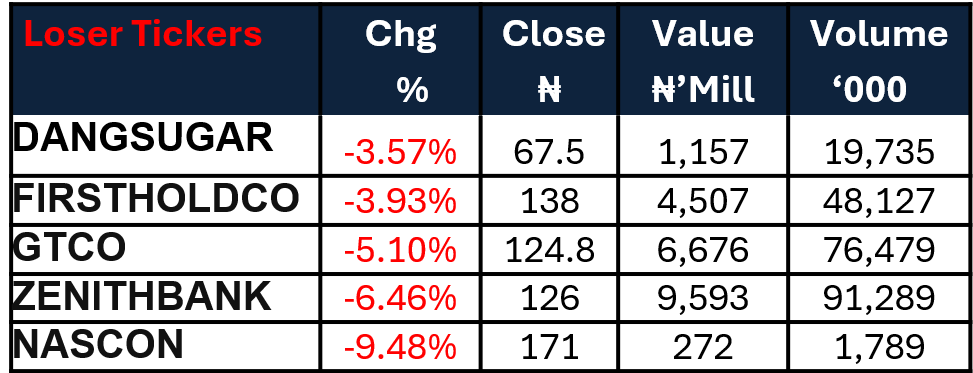
The ASI declined 0.33% WoW, marking its third consecutive weekly loss as selling pressure in heavyweight stocks outweighed improving market breadth. Banking (-3.15%) led declines, pressured by ZENITHBANK, GTCO and FIDELITYBK, while Oil & Gas (+3.13%) outperformed, supported by gains in ARADEL.
NTB Auction Result:
| 91-day | 182-day | 364-day | |
| Sales (₦‘bn) | 19.521 | 29.544 | 219.996 |
| Stop Rates | 15.50% | 15.80% | 15.90% |
FI Weekly Snapshot
| Bonds | Open | Close | WoW |
| % | % | (Bps) | |
| Feb-31 | 16.65 | 17.00 | (35) |
| Jun-32 | 16.65 | 17.00 | (35) |
| May-33 | 16.65 | 17.00 | (35) |
| Jul-34 | 16.65 | 17.05 | (40) |
| Jan-35 | 16.70 | 17.05 | (35) |
| Sep-36 | 16.70 | 17.05 | (35) |
| Apr-37 | 16.70 | 17.05 | (35) |
| Jun-38 | 16.70 | 17.05 | (35) |
| NTB & OMO | Open | Close | Effective Yield |
| % | % | % | |
| 14-Oct-27 | 15.70 | 15.60 | 18.46 |
| 22-Jun-27 | 16.15 | 16.05 | 18.01 |
| 06-Apr-27 | 17.10 | 16.90 | 18.35 |
Indices Watch 1-Yr Performance %
NSE 30 : Gainers and Losers
The Week Ahead…
The forthcoming bond auction will take center stage, with the DMO offering ₦1.75tn across the 19.00% Feb-2034, 16.79% Sep-2036, and 15.45% Jun-2038 re-openings. Scheduled inflows of c. ₦2.71tn from the 16.25% Apr-2037 coupon and OMO and NTB maturities should support liquidity and demand. The auction outcome will set the tone for secondary-market activity, while the balance between these inflows and settlement debits will shape liquidity through the week.
. For equities, We expect selective bargain hunting and Q3 earnings positioning to support market activity, with easing inflation and improved breadth providing some optimism. However, sustained recovery will depend on renewed demand in banking heavyweights and broader market participation.